A sport court appraisal does not add up what you paid for the court. The appraiser compares your home with recent nearby sales and adjusts for the court only as far as local buyers pay more for one. Permits, good condition and clear paperwork help the report give your court the credit the market supports.
Key Takeaways
- Appraisers value a court by market reaction, not cost. Fannie Mae requires market-based adjustments and does not accept appraisals that rely on the cost approach alone.
- From November 2, 2026, every new appraisal submitted for a Fannie Mae or Freddie Mac loan must use the redesigned UAD 3.6 format, which lists Sports Court as its own amenity.
- Recent local sales set the number. A court earns the most support where similar homes with courts have sold recently.
- Permits, a one-page fact sheet, maintenance records and good photos help the appraiser verify what they see.
- If the report misses or misdescribes the court, the borrower can ask the lender for a reconsideration of value.
How Does a Sport Court Appraisal Work?
Most mortgage appraisals rest on the sales comparison approach. The appraiser picks recent sales of similar homes, then adjusts each one up or down for differences in size, condition and features such as a court.
Fannie Mae’s Selling Guide, which lenders follow on loans they sell to Fannie Mae, requires at least three closed comparable sales. Sales that closed in the last 12 months should be used, and each one should appeal to the same buyers who would shop for your home.
Contributory Value, Not Cost
Appraisers talk about a feature’s contributory value. That is what the court adds to the price of the whole property in the eyes of buyers, which is rarely the number on your invoice.
Fannie Mae’s rules on adjustments to comparable sales say every adjustment must reflect the market’s reaction to the difference between two properties. The guide warns against rule-of-thumb figures that the local data does not back up.
In a sport court appraisal, cost counts less than many owners expect. Fannie Mae does not require the cost approach except for manufactured homes, and it will not accept an appraisal that relies on cost alone.
Why Nearby Sales Matter Most
The appraiser needs sales that show how buyers respond to a court. When a few homes with courts have sold nearby, an adjustment has support. When none have, the appraiser may look to a competing market area, which Fannie Mae allows, or the court may get a small adjustment or none.
If you are still weighing whether to build, our article on how an athletic court affects property value covers buyer appeal.
What the New Appraisal Report Records About Your Court
The appraisal report is changing. From November 2, 2026, every new appraisal sent to UCDP must use the Uniform Appraisal Dataset, version 3.6. UCDP is the portal Fannie Mae and Freddie Mac use to collect appraisals. Since January 26, 2026, lenders have been able to submit either the old or the new format.
The official UAD 3.6 delivery specification lists Sports Court as a named amenity. It defines one as an open or covered area built for multiple recreational and athletic activities. It sits in an Outdoor Accessories group with fences, outdoor kitchens and outdoor fireplaces.
| Report item | What it records | How to prepare |
|---|---|---|
| Amenity type | Sports Court, under Outdoor Accessories | List every sport that is lined |
| Area | The size of the court | Have length and width in writing |
| Material | What the court is built from | Name the surface system and base |
| Photos | Pictures of the amenity | Clean the court and clear the gear |
| Defects | Location, description and recommended action | Fix cracks, loose posts and peeling coating |
| Sales comparison | An Outdoor Accessories adjustment line | Point to nearby sales with courts |
In short, the court gets its own entry in the report, so its size and condition end up on the record.
What Moves a Court’s Appraised Value Up or Down
Beyond sales data, three things shape how a sport court appraisal treats your court.
Neighborhood Norms
Fannie Mae expects improvements to fit the neighborhood. If a feature’s design, quality, size or condition causes market resistance, the appraiser must evaluate the effect on value and marketability.
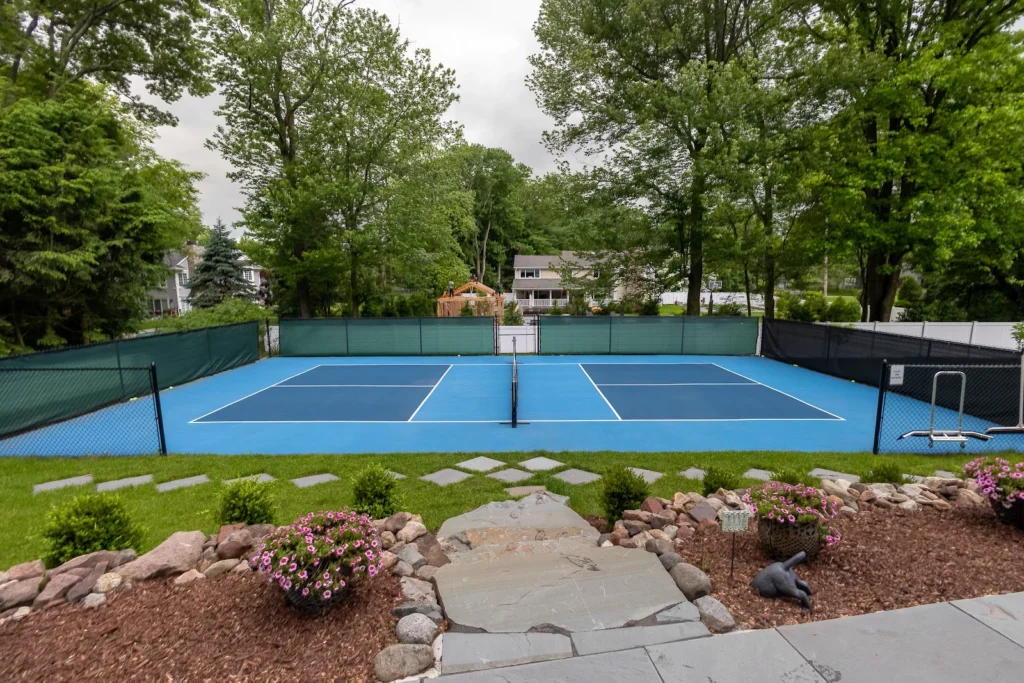
A half court on a street of large lots reads as normal. A full tennis court on a small suburban lot may be more court than local buyers want to pay for.
Condition on Inspection Day
The new report gives amenity defects their own fields, including where the problem is and what action is recommended. Visible problems such as cracks, standing water or a loose hoop could be recorded there.
Permits and Zoning
Fannie Mae tells appraisers who find an addition built without a required permit to comment on the quality and appearance of the work and its effect on value. An unpermitted court may draw similar questions. Our guide on when a backyard sports facility needs a permit explains the usual triggers.
Documents That Support Your Court’s Value
Appraisers rely on what they can see and verify. A tidy file turns “nice court” into facts a sport court appraisal can use.
| Document | What it proves |
|---|---|
| Permit and final approval | The court was approved and inspected where required |
| Survey or site plan | Where the court sits and its distance to lot lines |
| Builder specs and invoice | Size, base, surface system, lighting and fencing |
| Warranty paperwork | Any remaining coverage on surface or equipment |
| Maintenance log | Dates of resurfacing, crack repair and line painting |
| HOA approval letter | The association signed off, if you have one |
| Dated photos | Condition over time and the court in use |
Put the key facts on one page: dimensions, sports lined, surface type, year built, last resurfacing and permit number. Give copies to your listing agent or loan officer.
Planning a new court? Ask for the layout and specs in writing from day one. Our sport court construction process starts with measuring your space and a custom design, so you have the layout before building starts.
Tip: Federal lending rules let agents and lenders ask an appraiser to consider additional, appropriate property information, including comparable sales. They ban pressuring the appraiser toward a number, so share facts, never a target value.
Sport Court Appraisal Checklist Before You List
Work through these steps before listing photos are taken or an appraiser visits.
- Confirm the permit is closed and find the approval paperwork.
- Measure the court and write the one-page fact sheet.
- Seal cracks, clear drains and wash the surface.
- Repaint faded lines with our court resurfacing and line painting service or your own crew.
- Check hoop anchors, net posts, fencing and lights.
- Photograph the court in good light, both empty and in use.
- Ask your agent to feature the court in the listing and track nearby sales of homes with courts.
- Keep the court clear and easy to reach on appraisal day.
What If the Appraisal Misses Your Court?
Start by reading the report. For a first-lien home loan, Regulation B requires the lender to give applicants a copy of the appraisal. It is due promptly once the report is done or three business days before closing, whichever comes first, unless the applicant waives that timing.
When you refinance, that copy comes to you. When you sell, it goes to your buyer, so a missed court usually reaches you through the agents.
If the court was left out or described wrong, the borrower can ask the lender for a reconsideration of value, or ROV. Interagency guidance issued in July 2024 says an ROV request may include comparable properties not previously identified and property details that were reported wrong or never considered.
Keep the request specific and verifiable. Lenders can set their own rules, such as accepting only sales that closed by the appraisal’s effective date, so ask before you send anything.
Frequently Asked Questions About Sport Court Appraisals
Do appraisers count a sport court?
Yes, as a feature of the property. The redesigned UAD 3.6 report names Sports Court as its own amenity type, with room for its size, material, photos and any defects. Counting a court is not the same as adding dollars, though. The appraiser adjusts for it only as far as nearby sales show that buyers pay more for one.
Is there a standard dollar amount appraisers add for a court?
No. Fannie Mae requires each adjustment to reflect the local market’s reaction and warns against rule-of-thumb numbers the data does not support. So the same court can earn a real adjustment in one town and almost nothing in another. It depends on recent comparable sales and how buyers there value courts.
Does a sport court raise property taxes?
A lender’s appraisal and your property tax assessment are separate processes. Your local assessor decides how site improvements such as courts are treated, and practice varies by state and town. Call the assessor’s office before you build, and keep your permit on file either way.
Can I give the appraiser information about my court?
Yes, usually through your agent or loan officer. Federal Truth in Lending rules let lenders, agents and other covered parties ask an appraiser to consider additional, appropriate property information, including comparable sales. They cannot pressure the appraiser toward a value. A one-page fact sheet with dimensions, permit details and maintenance dates is the right kind of help.
Should I repair my court before the appraisal?
Fix anything an appraiser could record as a defect, such as cracks, standing water, peeling coating, loose posts or a hoop that wobbles. The redesigned report records amenity defects with their location and a recommended action. Fresh lines and a clean surface also help the court look its best in listing and appraisal photos.
Get Your Court Ready for the Appraiser
Selling or refinancing soon? Our crews handle crack repair, resurfacing, line painting and hoops across New Jersey, New York, Connecticut, Austin and Houston, and we build new residential sport courts too. Tell us about your court and your timeline.